

Serial acquirers have become increasingly popular in the financial world, especially among retail investors. While I agree that some of these companies have had terrific success, the question people have to ask themselves is whether these stocks will offer similar returns over the next few years. With starting valuations significantly above what they used to be, I argue that high starting valuations will, and already have, led to disappointing returns. However, I have found a company that fits the serial-acquirer category, has a terrific track record spanning more than three decades, and actually trades at a low starting valuation. Over the past two weeks I have started to build a position in DCC plc, as I believe we are presented with an excellent opportunity for long-term investors. In addition, the company is in the process of a transformational change that will lift the business to new highs and benefit shareholders tremendously.
Get yourself a cup of coffee ☕️, lean back and enjoy this write-up
[1.0] Overview
DCC is a UK-listed company headquartered in Ireland that operates primarily in the business of energy distribution. The energy division breaks down into two main segments: Services and Mobility. In Services, DCC supplies liquid fuels, LPG, heating oil, biofuels, electricity and natural gas. Under the Certas brand the company distributes ~4 billion litres annually (UK & Ireland) and is the de facto market leader in the region. DCC operates across most parts of fuel distribution as can be observed with the sizable tanker fleet, strategically located depots, third-party and own-brand lubricants, etc.
DCC is also expanding into renewables via solar PV, heat pumps and energy-efficiency solutions. The group operates (and in some cases owns) a network of 1,173 petrol stations and has long-standing partnerships with Shell, Esso, Texaco and Gulf. Across the entire energy business, DCC serves roughly 10 million customers and distributes ~15.2 billion litres of fuel annually across 21 countries.
DCC currently holds a 7% share of the EU photovoltaic market. In liquid fuels, the company commands roughly 30% market share in its key markets and ranks among the top three players in the UK, Ireland, France, Germany and the Nordics. The Energy division contributes ~86.7% of the group’s adjusted operating profit, while the Technology business makes up the remaining ~13.3%
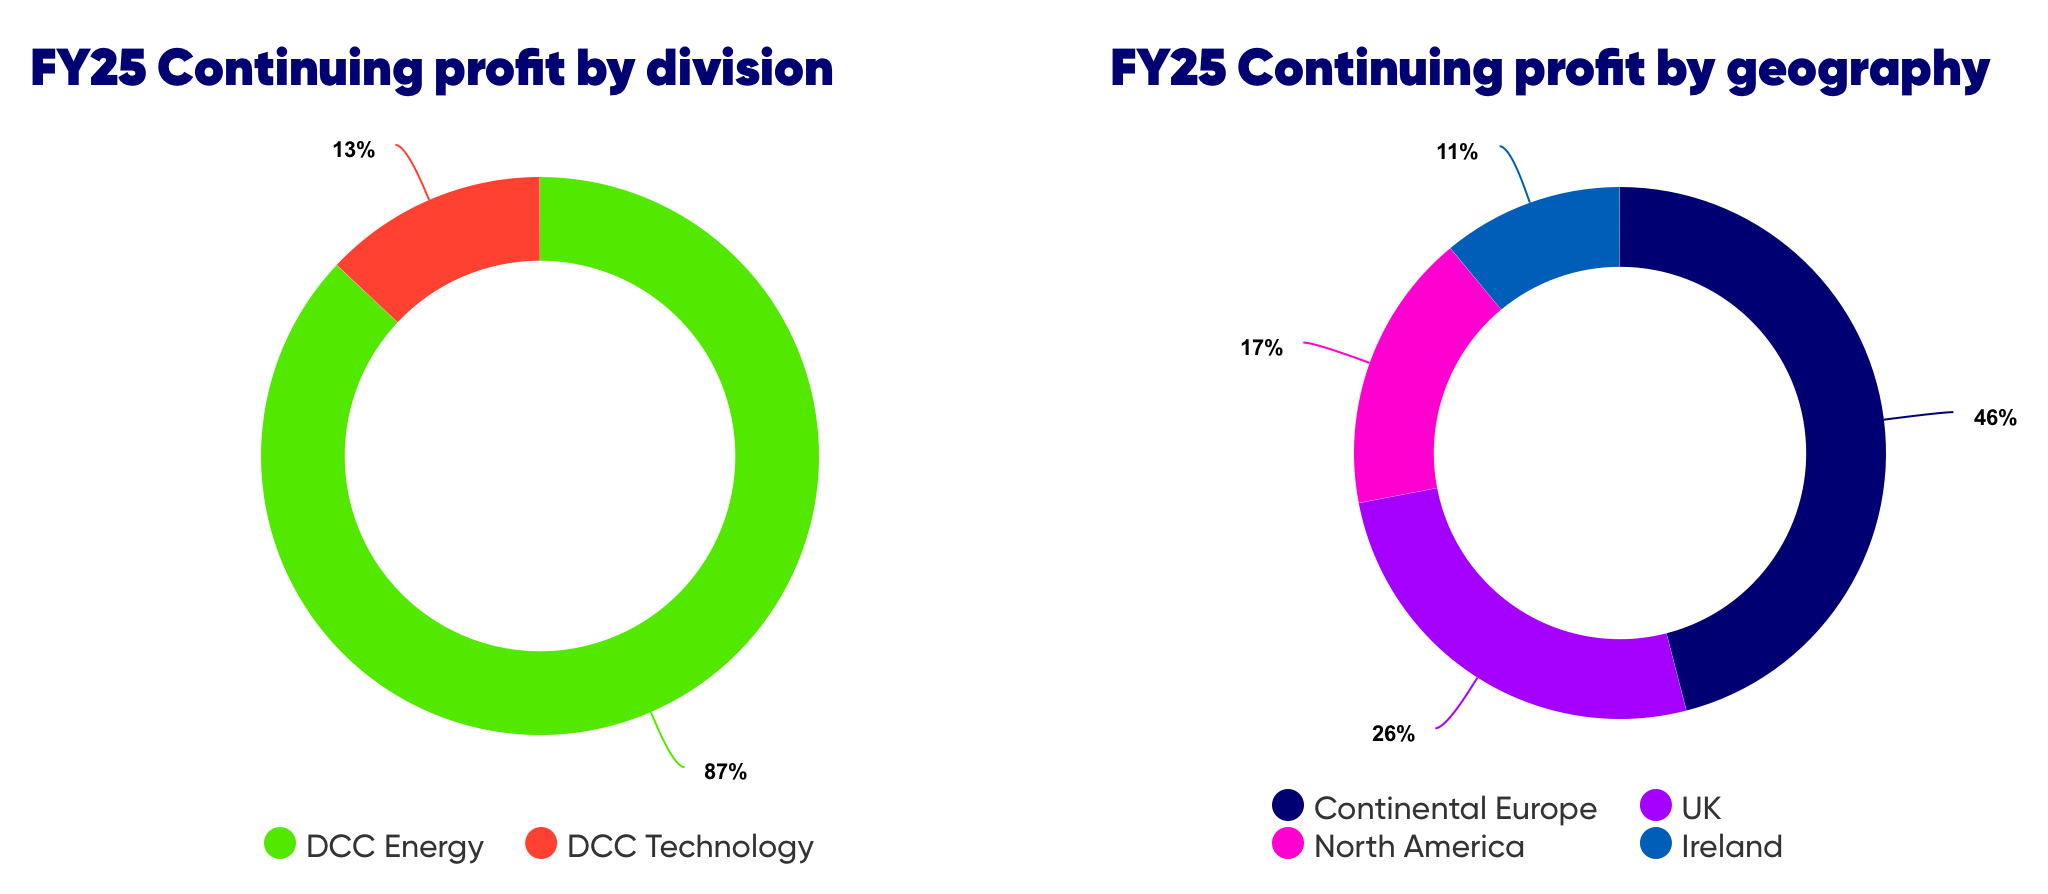
[DCC’s financial year ends on March 31st. For clarity, this report will refer to the financial year ending March 31, 2025, as FY25.]
[1.1] Technology business and the group’s geographical footprint
The Technology business can be broken down into two parts:
ProTech: The largest specialist distributor of professional audio-visual and communications technology in the world by revenue. Products include displays, projectors, video walls, pro-audio equipment and related infrastructure.
InfoTech: The group’s UK & Ireland-focused IT distribution business, operating primarily under the Exertis brand. It distributed a wide range of products ranging from laptops to routers and TVs.
DCC shifted its focus from conglomerate-like economics to a focused energy distribution business. The InfoTech division had very low margins, which resulted in the sale of the company to Aurelius for £100 million in July 2025.
From a geographical perspective, the UK is by far the largest contributor to the group’s revenues, contributing 32.4% of revenues for FY25. The French business under the Butagaz brand is the second largest liquid gas distributor in the country, contributing 17.7% of the group’s revenues. The U.S. and Ireland make up 10.5% and 10.2% respectively, while the U.S. market is seen as a significant opportunity for growth in the distant future. The rest of the world accounts for the remaining 29.2% of revenues.
[2.0] Transforming a conglomerate
Over the course of its history, DCC has been involved in many different businesses (healthcare, waste management, food, etc.). This wide range of business ventures has resulted in conglomerate-like economics with resilient earnings but very little focus on the core of the group’s expertise. Today, DCC is mainly focused on what they do best: energy. An energy focused firm from Europe has to be among the most hated business descriptions in the financial industry. However, DCC has proven its worth. The firm has grown operating profits and dividends at a 13% CAGR over 31 years. Furthermore, operating profits grew every year except for one outlier in 2012 (profits reverted to new all-time highs the next year).
The market for liquid fuels is highly fragmented, which creates significant opportunities to expand through acquisitions. To capitalize upon this opportunity, you need capital. DCC is well capitalized and is able to fund itself without having to tap credit markets. In case the company wants to participate in a major deal, DCC has credit lines and relations with major banks, while also having a balance sheet mainly consisting of low-interest, fixed-rate debt. While energy is hated, the industry dynamics and economics are indisputable. DCC is not in the business of taking risks on oil or electricity prices. DCC acts as a middleman that uses its vast network of customers and suppliers to match supply and demand while creating value for both customers and partners. Over time, the strategy of growing through acquisitions has paid off. On average, the company has been involved in 13 acquisitions p.a. since going public in 1994.
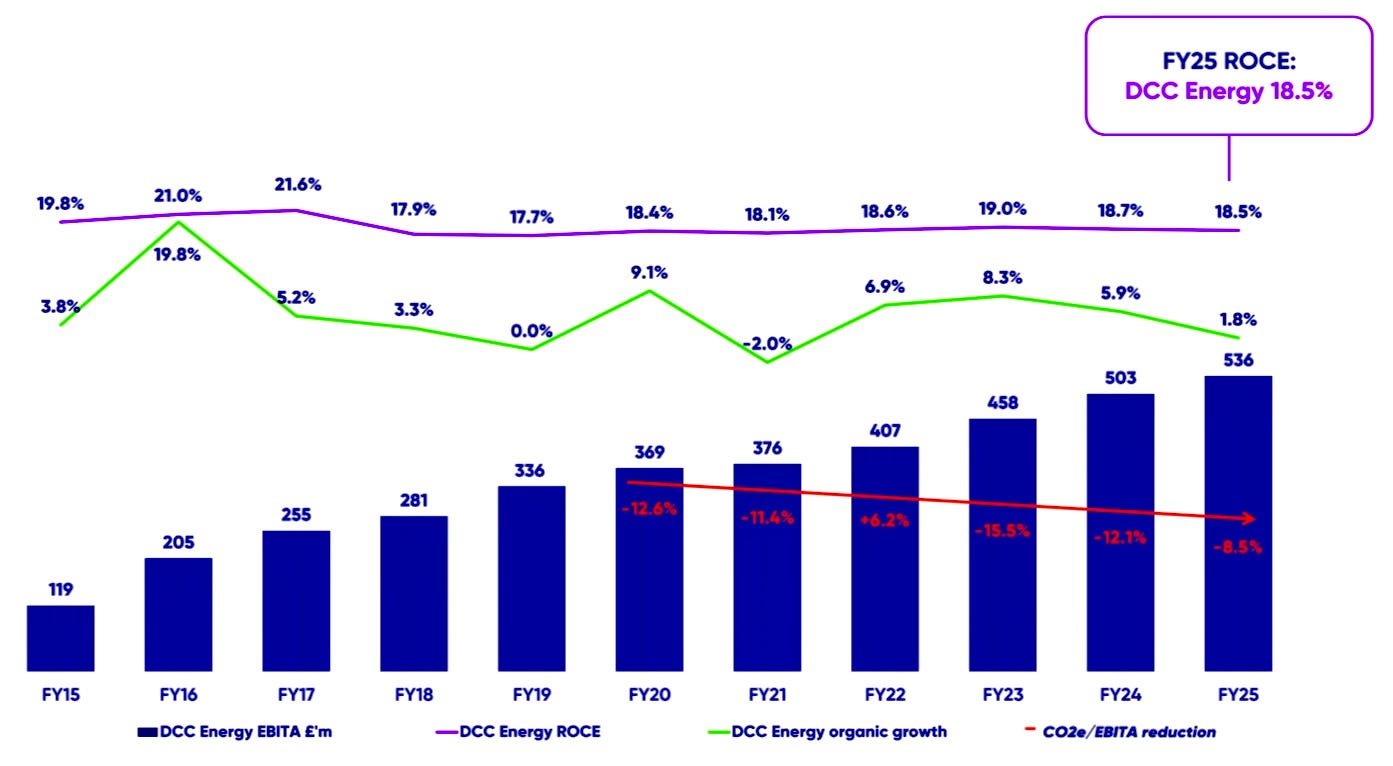
What makes the energy business stand out is the fact that the division has achieved an average ROCE of 18.2% over the past 10 years. With these numbers, the energy business is the most efficient division of the group (consisting of energy, tech and healthcare).
[2.1] Divestments and Buybacks
The key step towards a leaner organization is the announced sale of both the Healthcare and InfoTech business for £945m and £100m respectively. As part of these transactions, DCC will return most of the proceeds to shareholders via buybacks. The £100m share buyback is already completed while the company announced a tender offer worth £600m that will commence in November of this year. Another £100m are expected to be returned to shareholders “following [the] receipt of unconditional deferred consideration payable for DCC Healthcare in approximately two years.“
Furthermore, the company announced a review of the remaining Technology business over the next 12 to 24 months, leading me to think they intend to dispose this business. Currently, Technology is struggling to find itself, which isn’t a problem limited to DCC but the entire industry. If the company can increase profitability and sell off ProTech, the value could be immense. The bottom line of these transactions is that DCC has finally realized that they should focus on what they can do best: consolidate a highly fragmented industry.
[3.0] Incentives
As investors, we want management to be on our side and be aligned with us. Therefore, we will quickly break down the incentive structures for DCC‘s management team before going over to the actual financials. As can be seen below, CEO Donald Murphy and COO Kevin Lucey are encouraged to hold shares in the company worth 3x and 2x their base salary respectively.
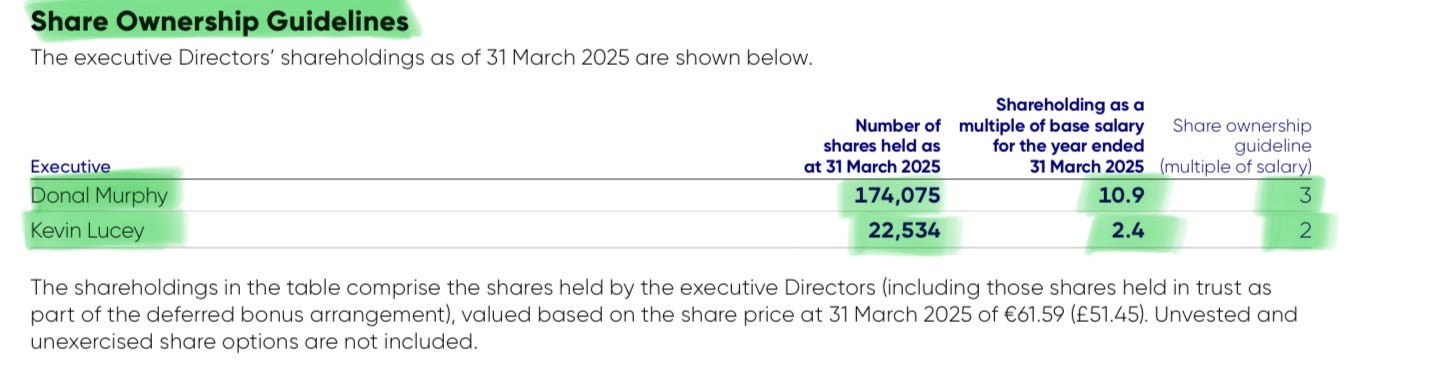
Both of them are above this threshold, while Donald Murphy stands out, holding 174,075 shares valued at ~10x his yearly base salary. Apart from holding a decent number of shares, the management team can reap bonuses and long-term incentive plans (LTIPs) worth several times their base salaries in case DCC performs well.
“For the year commencing 1 April 2025, LTIP awards of up to 250% of salary will be granted to the executive Directors. The grant value is expected to be up to 250% of salary for the Chief Executive, up to 225% of salary for the COO and up to 200% of salary for the new CFO. The extent of vesting will be based on performance over the three financial years ending 31 March 2028, with a further two-year post-vesting sale restriction also applying.“
— DCC plc FY 2025 Annual Report
The bonuses are capped at 200% of base salary for both the CEO and COO and 150% for the new CFO. The measurement of success will, as last year, be based 70% on adjusted operating profit growth and 30% on strategic objectives (e.g., 15% strategic progress and 15% ESG).
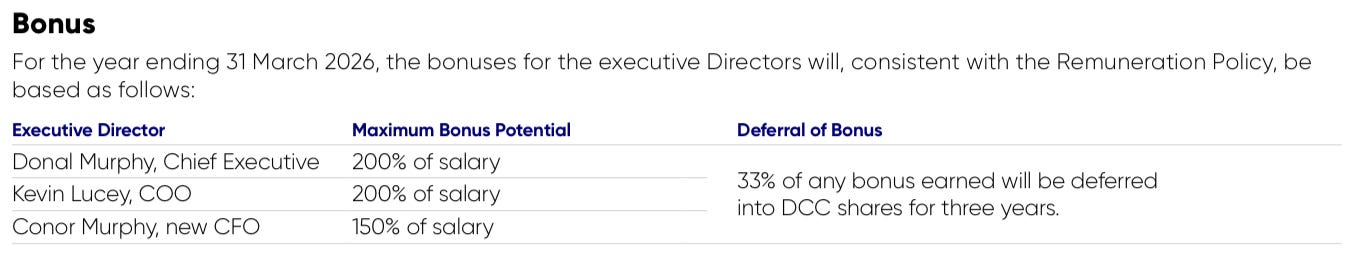
Sadly, we don’t know the exact details for the thresholds, as the company only reports them next year, due to it being classified as confidential information. We do know, however, the thresholds for last year, which were based on 7% adjusted operating profit growth and some other strategic and ESG factors.
The LTIPs are based on three key components. ROCE and EPS growth make up 40% of the total grantable amount each, while TSR (Total Shareholder Return) is responsible for the remaining 20%. Last year the targets to receive the maximum allocation were based on 15.5% ROCE and 9% EPS growth (on a continuing basis). Furthermore, DCC plc‘s TSR would have had to be among the upper quartile of the FTSE 100.
For this year, we don’t have exact figures yet, as the Committee decided to postpone the decision for setting the targets until later in the year.
“The Committee took a decision to postpone the setting of the threshold and maximum target ranges for each of the performance conditions until later in the year, to allow additional clarity in relation to certain divestments taking place as part of the Company's revised strategy to emerge. The threshold and maximum target ranges for each of the performance conditions will be announced later in the year once they have been determined.“
— DCC plc FY 2025 Annual Report
Below we can see a breakdown of the potential remuneration for FY 2026 under different scenarios.
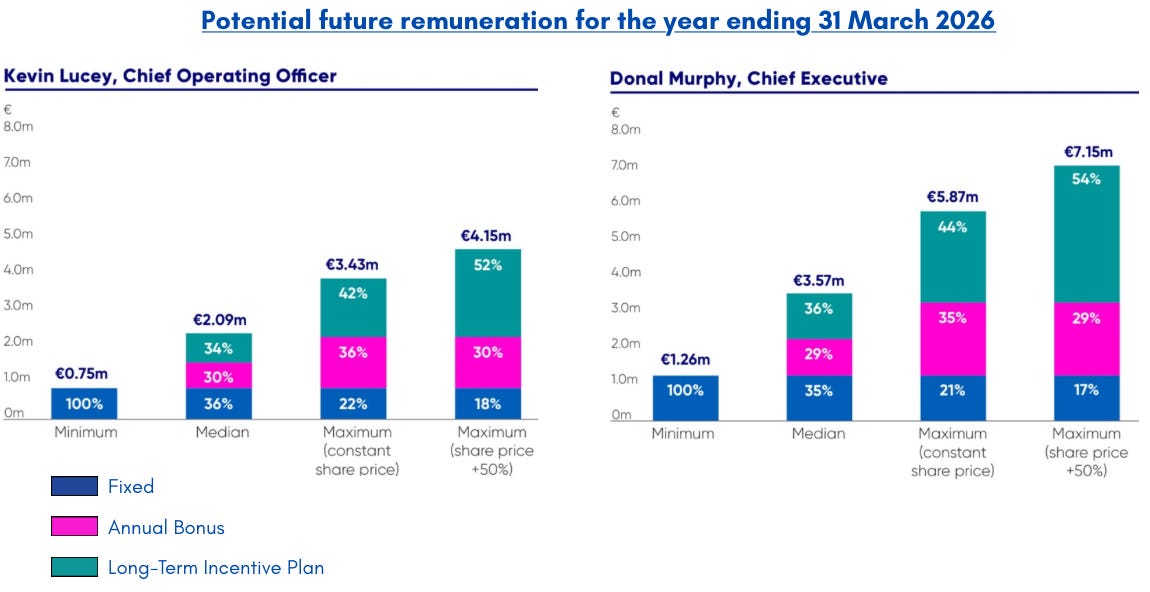
Clearly, there is an incentive for management to deliver. While we don’t have clear thresholds yet, we should receive these in a few months.
[4.0] Financials and Liquidity Profile
After having talked about the business, the incentives and transformative changes, we have to break down the cash flow statement to get a sense of how much cash the business is generating. Furthermore, the question is how much capital there is for additional acquisitions and shareholder returns.
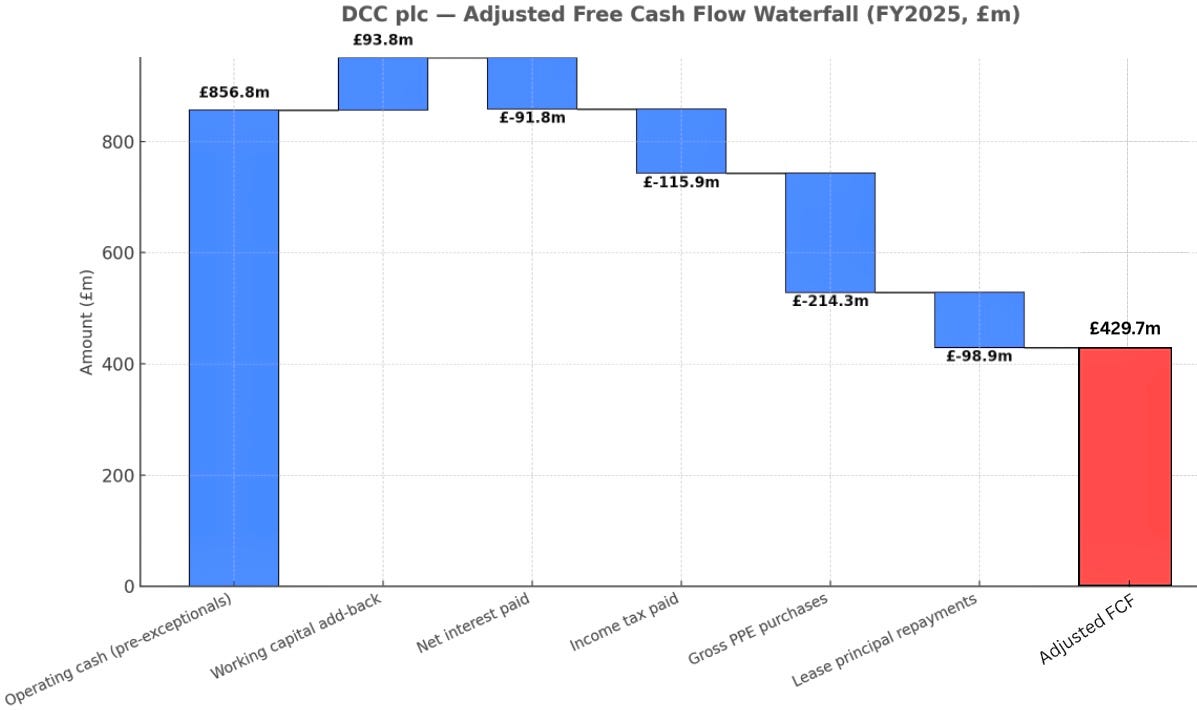
In FY 2025, operating cash flow pre-exceptionals came in at £856.8m. My definition of free cash flow adds back changes in working capital as these are often very volatile in nature. If we add back the changes in working capital and subtract net interest paid as well as taxes, we arrive at £742.9m.
Furthermore, I subtract investments into property, plant and equipment, as well as lease principal repayments, because these are real expenses. Some people don’t treat lease principal repayments as expenses, but I think it all comes back to how you treat leases on the balance sheet. If I include leases in net debt, I don’t necessarily have to subtract lease principal repayments as expenses, because any repayment of lease principal increases equity. If, however, my definition of net debt is excluding leases (usually my definition), I should treat lease principal repayments as expenses. With that, we arrive at adjusted FCF of £429.7m.
[4.1] Balance Sheet and Liquidity
Apart from just the cash flow statement, the balance sheet of DCC shows a healthy and well capitalized company with a decent debt load and access to a lot of liquidity. As of FY 2025, DCC has net debt of £795m excluding leases and £1.15bn including leases. Since we subtracted lease principal repayments in the free cash flow calculation, it only makes sense to exclude leases from net debt now. Whether you choose to include leases in net debt or exclude them makes a small difference in Net debt/adjusted FCF from 1.84x (excluding leases) to 2.17x (including leases). Overall, DCC has healthy leverage ratios that aren’t inflated. In addition, DCC is a very stable and profitable business, solidifying my belief that it is a well and conservatively run company.
From a debt maturities standpoint, ~80% of the company’s borrowings are non-current. Of DCC’s non-current borrowings, 50.2% mature in over 5 years.
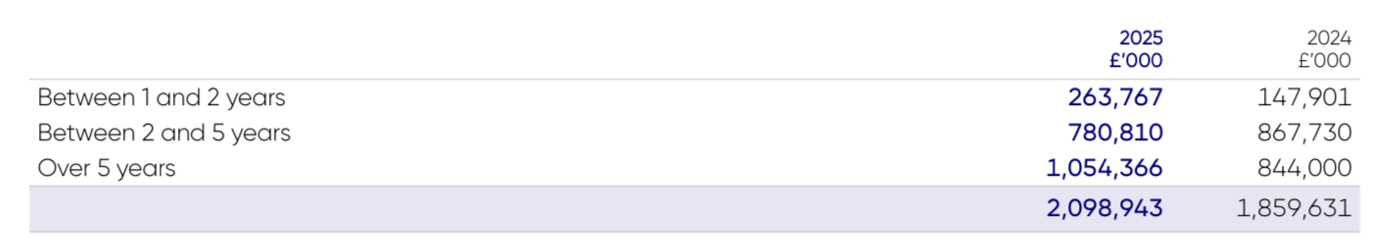
With the new euro bond placement at a fixed interest rate of 4.375%, 75% of the group’s debt is fixed rate with average interest rates of 5.29%, 3.87% and 3.49% for USD, GBP and EUR denominated borrowings respectively. As of FY25, the average time till maturity stands at 4.8 years.
To guarantee its financial stability and constant access to capital, DCC has an undrawn revolving credit facility for £800m in place. Furthermore, the company has shown its ability and willingness to raise capital from the global credit markets by refinancing £500m worth of debt with the first public bond placement in the company’s history in July 2024.
[5.0] Valuation and Risks
At the time of this writing, DCC plc is trading at £47.14 a share and has ~96.9m shares outstanding following the completion of the £100m share buyback program earlier this month. The current market cap and EV stand at £4.57bn and £5.72bn respectively. As previously mentioned, the company will launch a £600m tender offer in November. If we assume (conservatively) that DCC will repurchase these shares at £54 a share (15% premium), this would reduce the share count by 11 million shares to ~86m shares. On the current share price, we are buying shares at a market cap and EV of ~£4bn and £4.8bn respectively following the tender offer. Earlier, we broke down the cash flow statement and arrived at £430m adjusted FCF for FY25. Based on available data, the discontinued operations accounted for roughly 10.7% of operating cash flows and CAPEX. If we assume the same for cash flows (limited disclosures), pro forma FCF stands at ~£385m. Based on these numbers, DCC plc is currently trading at 10x pro forma P/FCF and 12.5x pro forma EV/FCF.
While the core of the business and my thesis are built around the Energy distribution business, the remaining Technology business should not be forgotten. Just to show how much this part of the business should be worth, DCC acquired the U.S. appliance distributor Almo in late 2021 for $610m.
If we look at some publicly traded peers such as Avnet, the largest distributor of electronic components globally, we would have to value Pro Tech at 11x EV/adjusted EBIT or ~£800m. It’s difficult and unnecessary to try to calculate the exact value of ProTech, because rough estimates are all we need. I personally consider ProTech valuable enough to erase the entire present net debt of DCC. Considering that DCC has already announced a strategic review of the Technology business, I wouldn’t be surprised if the company announces the sale of the remaining Technology business at some point over the next 12 to 24 months.
[5.1] Risks
I generally see DCC as a stable and low-risk investment, but every investment bears risks. One red flag I note in DCC’s reporting and IR material is the focus on ESG. Don’t get me wrong, ESG has some importance, but as a public company the main focus should be on shareholders and execution, not on Co2e/EBITA metrics. The second point to monitor is execution of the M&A strategy. While DCC has decades of experience, a couple of bad deals could leave a lasting impact. M&A is an opportunity but always a risk. However, I don’t have any datapoint that makes me concerned about this as of now. Overall, DCC seems like a stable, well-run business with no obvious, immediate threats.
[6.0] Conclusion
In conclusion, DCC plc offers a compelling opportunity to buy a business with a proven track record of growth at an attractive price and a starting dividend yield of 4.3%. With a strong balance sheet, significant free cash flows and a leading market position in European energy distribution, DCC is well positioned to grow profitability at around 10% p.a. for many years to come. The management team is aligned with shareholders, and a potential sale of the remaining Technology business is a possible catalyst over the next 12–24 months.
I have been building a position in DCC plc and would gladly welcome a pullback to increase my holding.
Yours sincerely,
MODERN INVESTING
Thanks for the write up - very interesting.
One thing I am not sure on though is how to think about the valuation you discuss?
Assuming you are right and the Tech business sale wipes net debt, then it is trading c.10x EV/FCF? But what should we be paying for a fuel distributor? As someone who doesn’t know this businesses or industry just trying to get your perspective on the valuation context.
Just from what you’ve written this doesn’t look to me like a massive anomaly that will reveal itself post-tender offer as to the implied valuation of the distribution business. But maybe I’m wrong?
Relatedly, you imply that DCC fuel distribution is a fundamentally good business (high ROE) but how does it compare to competitors? Any peers to look at?
Thanks!
"As of FY 2025, DCC has net debt of £795m excluding leases and £1.15bn including leases. Since we subtracted lease principal repayments in the free cash flow calculation, it only makes sense to exclude leases from net debt now."
If you subtract lease payments you are making them "CF relevant" why not include for balance sheet figures - you are understating net debt.
What am I missing ? For me it looks like an apples to oranges issue.