

Where do I start? Metlen is giving me mixed feelings. On one side the company is perfectly positioned to benefit from the biggest shift in European politics since WW2. On the other side I have to question the management team because their transparency is nonexistent. Whether you are a shareholder or just watching, this quick piece breaks down the profit warning and recent defense and construction developments.
Entirely free to read
1. The Profit Warning
On Friday Metlen issued a profit warning stating that EBITDA will probably come in 25% below expectations, or about €750m instead of €1bn. The reason for that is twofold. Firstly, Metlen anticipated realizing the sale of several solar projects for the year 2025, which did not happen. A major solar sale was announced days later, pushing that EBITDA into 2026 instead of 2025. Secondly, cost overruns and delays at the Protos EfW Energy from Waste project in the UK have impacted operating results.
The timing issue surrounding the sale of solar projects is nothing to be concerned about. A few days earlier Metlen reported selling 283 MW of solar projects to Schroders Greencoat. What caused the brutal reaction by investors on Friday were cost overruns at Protos EfW, which have been haunting the company since mid 2025.
“During the first half of 2025, M Power Projects’ performance was driven by challenges encountered in the Protos project, where unforeseen issues disrupted execution, resulting in increased costs and extended timelines beyond initial expectations. Specifically, a major workplace third-party accident played an important role in further exacerbating these disruptions, causing substantial delays and multiple work stoppages. These challenges were compounded by the bankruptcy of a key subcontractor and the subsequent withdrawal of another from all its regional operations. […] The Company continues to monitor and actively manage these issues and has fully accounted for their financial impact in the period’s results and for the entire financial year 2025.“
The Protos project is a waste to energy facility that is supposed to generate 49 MW of electricity per annum once operational. Metlen and the Japanese industrial conglomerate JFE, through its subsidiary Standardkessel Baumgarte GmbH, are constructing the project in Cheshire, UK.
While cost overruns are painful, they are not extraordinary for large construction projects. The crucial part here is that management clearly stated that they assumed no further negative impacts from cost overruns at Protos. That proved false, shocking investors and triggering a 20 percent drop in the share price. Considering the size and asset base of Metlen, the selloff has more to do with loss of trust in the management team than the lower guidance. And there is no way to rewrite this. Making errors is part of the game. Being diversified helps mitigate the impacts. But not even posting the guidance cut on the IR page was an attempt to portray the company in a polished way.
2. A Developing Defense & Construction Story
In between all this drama, Metlen has been hitting milestones in other parts of the business ranging from defense to construction. The core thesis on Metlen from December has not changed. The company is in a fabulous position to benefit from remilitarization efforts in Europe while the competition has gone bankrupt due to high energy costs.
“The aluminium production in Europe has actually fallen to its lowest level since 1970s as the soaring energy costs delivered a severe blow to this energy-intensive sector. Norsk Hydro, another large-scale aluminium smelting enterprise, also planned to close one of its smelters in Slovakia before the end of September.“
Apart from aluminium production, the group has been expanding aggressively in the defense sector, cooperating with the French Naval Group and German Rheinmetall. In January the group reported having acquired its sixth facility for the production of defense equipment. At its capital markets day in April last year the company stated the goal of growing to five production facilities within three to five years. Less than one year later the company has surpassed this goal.
Furthermore, in early February Metlen and Naval announced the successful delivery and integration of Metlen’s supplied electrics and hydraulic systems into the French navy.
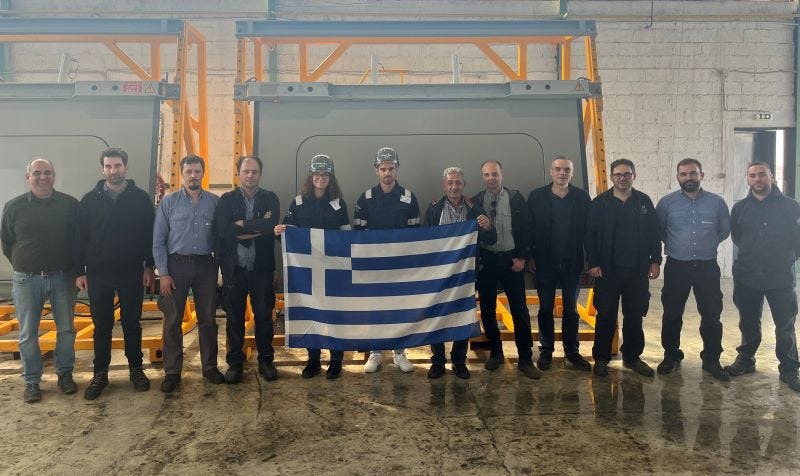
Apart from defense, the company’s subsidiary METKA recently announced a transformative deal for the construction and concession of a 187 km highway in Crete connecting Heraklion, Chania and Kissamos. The project is considered the largest highway under construction in Europe, with estimated construction costs of about €2bn.
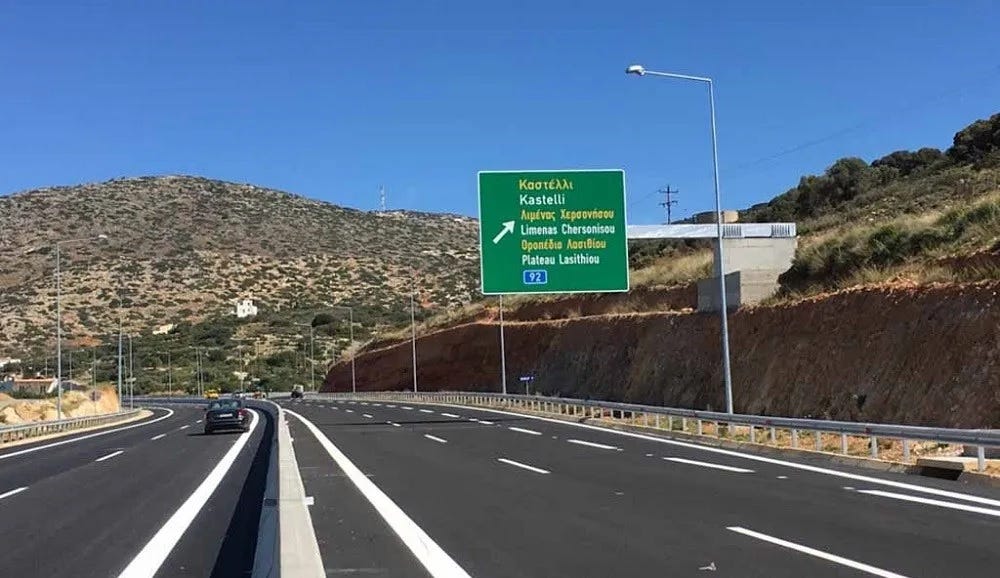
METLEN holds a 24% stake in both the concession and operation while its construction arm METKA maintains a 30% share in the project’s design and construction joint venture. Partners include GEK Terna (largest construction firm in Greece) and Aktor.
3.0 Conclusion
So what is the bottom line? Metlen’s drop in share price is not about a massive structural shift in the fundamental business. Neither has the growth in defense and construction slowed down. The issue is a direct response to management’s failure to be transparent and realistic about the delays at Protos EfW. What is truly confusing is the fact that Metlen’s chairman Evangelos Mytilineos bought shares worth millions of euros in December in the low 40s.
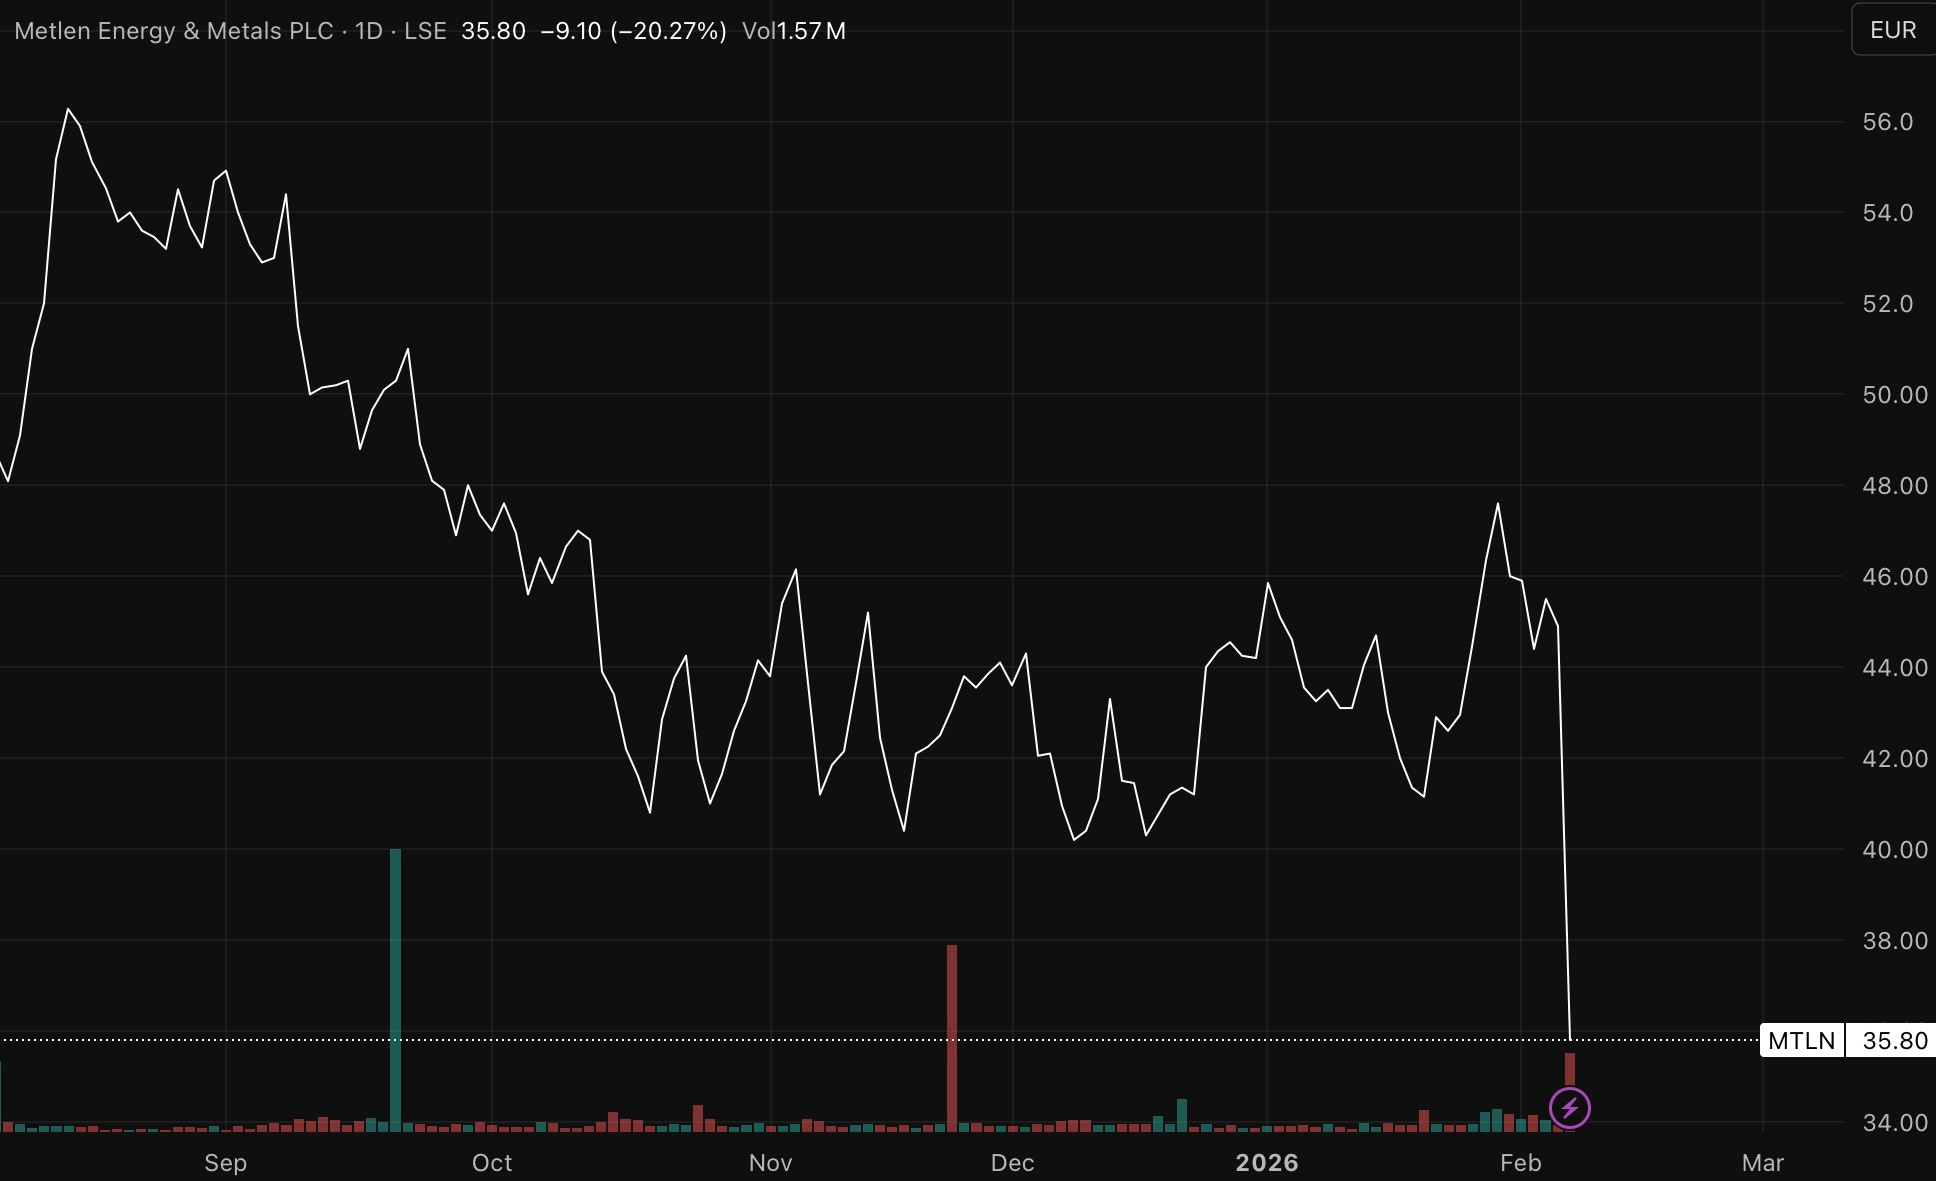
As the share price hit the mid 30s on Friday, Mytilineos is down significantly on these purchases. Some people pointed out that the buying could be just PR to create the illusion of a bullish setup. I have trouble believing it, as he is down several hundreds of thousands of euros and did not profit from the selloff. Of course everyone can have their theories, but I feel like the company’s management was overly confident and realized the mistake too late. Instead of doing the right thing and being totally transparent about it, posting it on the IR page and explaining everything clearly, management attempted to stay silent. This has caused the market to lose trust in the business and punish the share price significantly.
Markt Twain summarized it beautifully:
"It ain’t what you don’t know that gets you into trouble. It’s what you know for sure that just ain’t so."
— Mark Twain
And yet, with all the obstacles, I decided to pull the trigger. I bought a small position in Metlen on Friday. Was this the correct decision? I don’t know. I just know that the setup Metlen has is unique. Opportunities to buy businesses like this at such low valuations are never straightforward. There is always something that causes the undervaluation. Either you know about it at the moment in time or you do not. My personal mantra is to demand supply when everyone is selling. I will look back at this decision and either be grateful for having used the chance or laugh at my stupidity. For now it is a 2% position.
Yours sincerely,
Oliver Stencel